Retirement

Understanding the SECURE Act 2.0

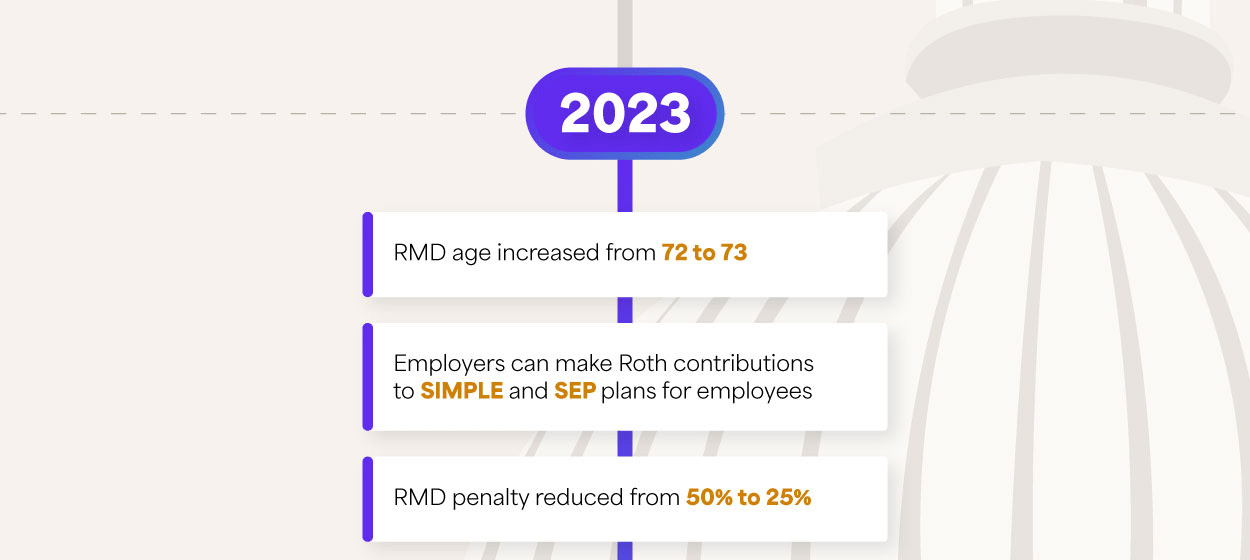
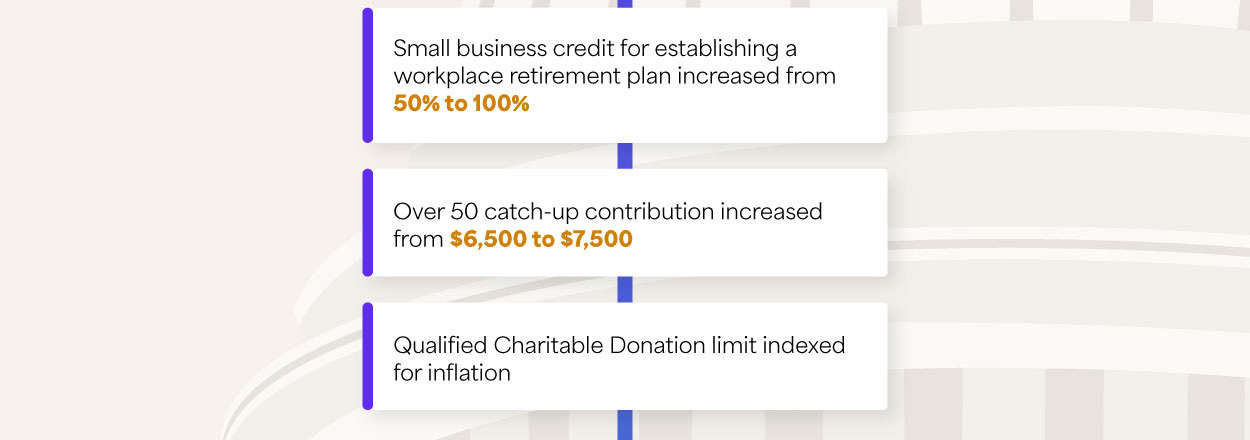
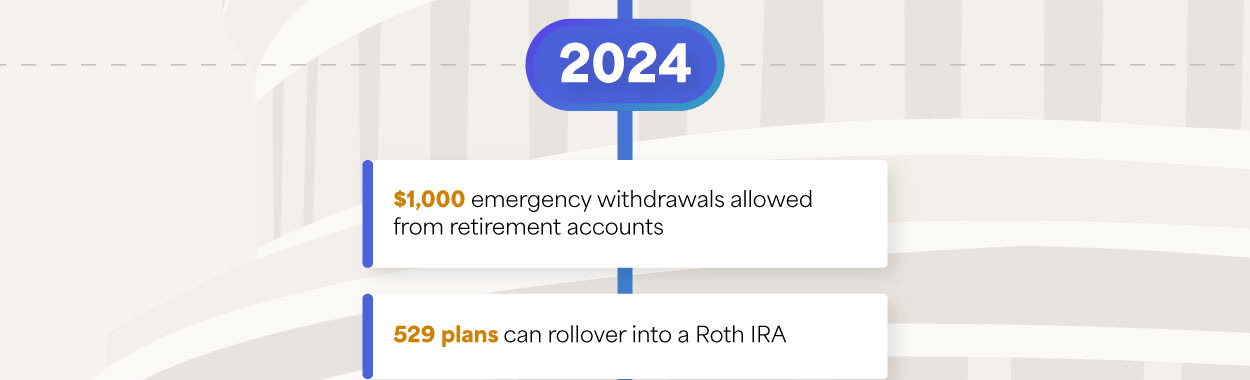
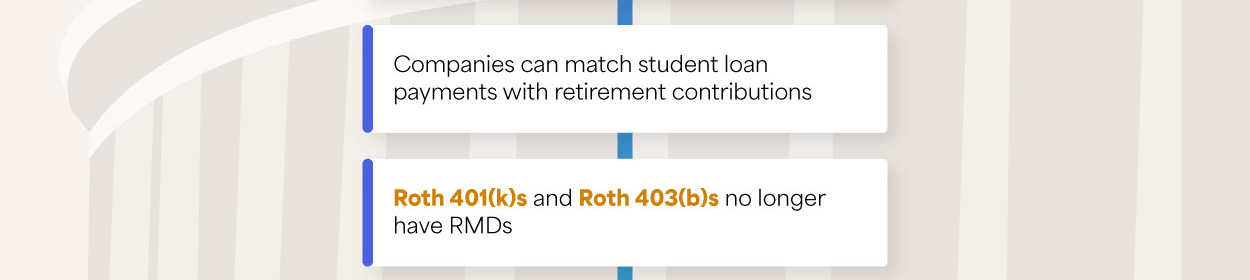
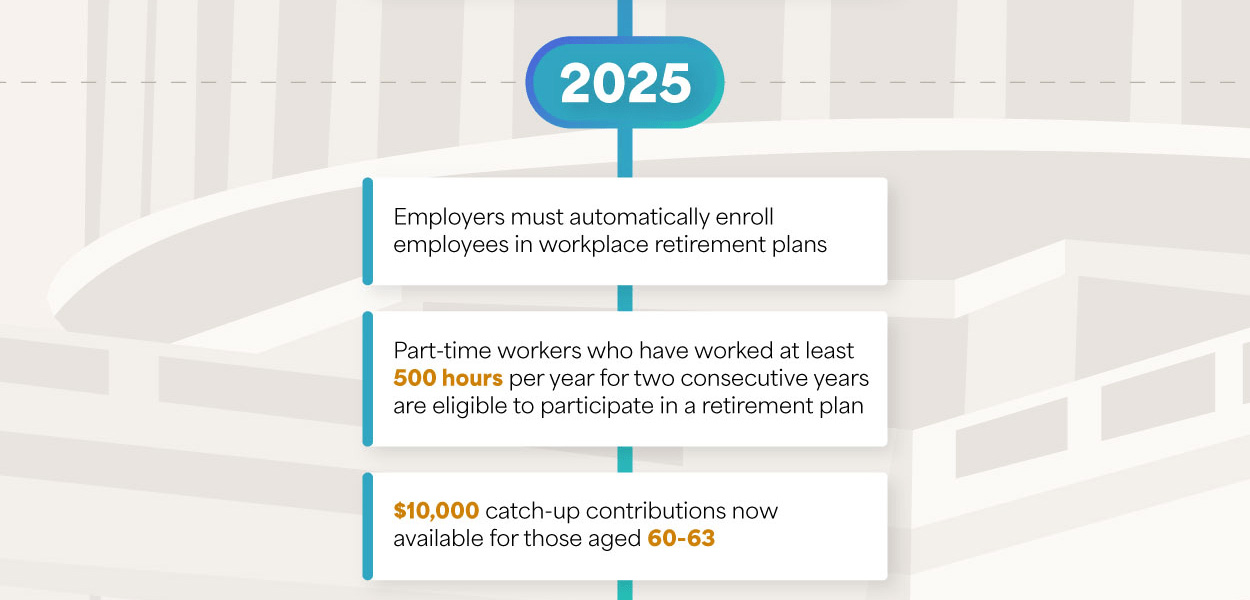
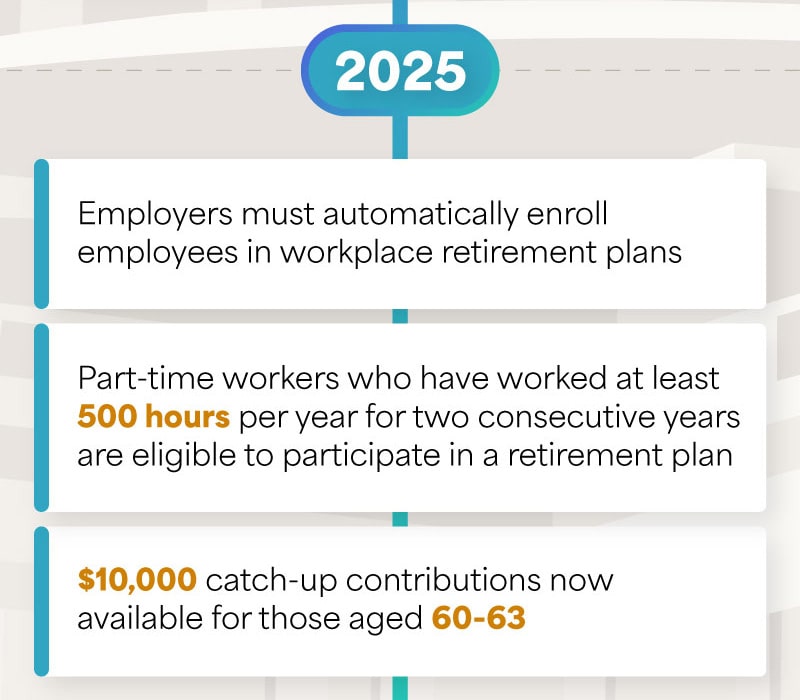
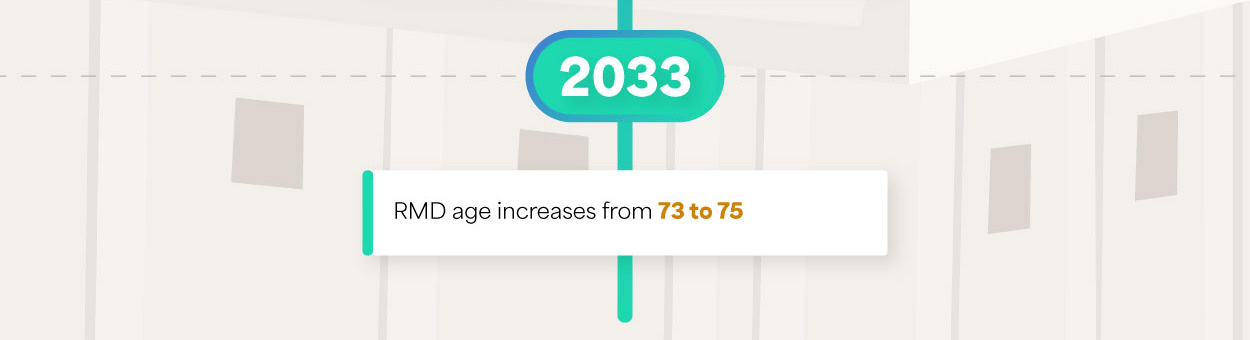
This infographic is composed of a timeline that moves vertically down the page starting in 2023 and ending in 2033. The title is placed next to a vector image of the US Capitol spire and reads: Secure Act 2.0.This infographic is composed of a timeline that moves vertically down the page starting in 2023 and ending in 2033. The title is placed next to a vector image of the US Capitol spire and reads: Secure Act 2.0.Moving down the US Capital spire, underneath the title is text that reads: In the final days of 2022, Congress passed SECURE 2.0, the new set of retirement rules designed to facilitate contribution to retirement plans and access to those funds earmarked for retirement. This sweeping legislation has dozens of significant changes; here is a timeline covering a few of the major changes of the new law.Moving down the US Capital spire, underneath the title is text that reads: In the final days of 2022, Congress passed SECURE 2.0, the new set of retirement rules designed to facilitate contribution to retirement plans and access to those funds earmarked for retirement. This sweeping legislation has dozens of significant changes; here is a timeline covering a few of the major changes of the new law.Moving down the US Capitol dome, the timeline begins with 2023 and lists six changes: RMD age increased from 72 to 73. Employers can make Roth contributions to SIMPLE and SEP plans for employees. RMD penalty reduced from 50 percent to 25 percent.Moving down the US Capitol dome, the timeline begins with 2023 and lists six changes: RMD age increased from 72 to 73. Employers can make Roth contributions to SIMPLE and SEP plans for employees. RMD penalty reduced from 50 percent to 25 percent.Small business credit for establishing a workplace retirement plan increased from 50 percent to 100 percent. Over 50 catch-up contribution increased from 6,500 dollars to 7,500 dollars. Qualified Charitable Donation limit indexed for inflation.Small business credit for establishing a workplace retirement plan increased from 50 percent to 100 percent. Over 50 catch-up contribution increased from 6,500 dollars to 7,500 dollars. Qualified Charitable Donation limit indexed for inflation.Continuing down the US Capitol dome, the timeline progresses to 2024 and lists four changes: 1,000 dollars emergency withdrawal from retirement accounts. 529 plans can rollover into a Roth IRA.Continuing down the US Capitol dome, the timeline progresses to 2024 and lists four changes: 1,000 dollars emergency withdrawal from retirement accounts. 529 plans can rollover into a Roth IRA.Companies can match student loan payments with retirement contributions. Roth 401(k)s and Roth 403(b)s no longer have RMDs.Companies can match student loan payments with retirement contributions. Roth 401(k)s and Roth 403(b)s no longer have RMDs.Closer to the base of the US Capitol dome, the timeline transitions to 2025: Employers must automatically enroll employees in workplace retirement plans. Part-time workers who have worked at least 500 hours per year for two consecutive years are eligible to participate in a retirement plan. 10,000 dollar catch-up contributions now available for those aged 60-63.Closer to the base of the US Capitol dome, the timeline transitions to 2025: Employers must automatically enroll employees in workplace retirement plans. Part-time workers who have worked at least 500 hours per year for two consecutive years are eligible to participate in a retirement plan. 10,000 dollar catch-up contributions now available for those aged 60-63.At the base of the US Capitol dome, the timeline reaches 2033 with one final change: RMD age increases from 73 to 75.At the base of the US Capitol dome, the timeline reaches 2033 with one final change: RMD age increases from 73 to 75.The bottom of the infographic depicts part of the US Capitol dome, largely obstructed by text that reads: Retirement rules can change without notice, and there is no guarantee that the treatment of specific rules will remain the same over time. This article intends to give you a broad overview of SECURE 2.0. It's not intended as a substitute for real-life advice regarding your retirement strategy. Roth IRA distributions must meet a five-year holding requirement and occur after age 59½ to qualify for the tax-free and penalty-free withdrawal of earnings. Tax-free and penalty-free withdrawals are allowed under certain other circumstances, such as the owner's death. The original Roth IRA owner is not required to take minimum annual withdrawals.The bottom of the infographic depicts part of the US Capitol dome, largely obstructed by text that reads: Retirement rules can change without notice, and there is no guarantee that the treatment of specific rules will remain the same over time. This article intends to give you a broad overview of SECURE 2.0. It's not intended as a substitute for real-life advice regarding your retirement strategy. Roth IRA distributions must meet a five-year holding requirement and occur after age 59½ to qualify for the tax-free and penalty-free withdrawal of earnings. Tax-free and penalty-free withdrawals are allowed under certain other circumstances, such as the owner's death. The original Roth IRA owner is not required to take minimum annual withdrawals.
 

Related Content

Do Our Biases Affect Our Financial Choices?

Do Our Biases Affect Our Financial Choices?

Even the most seasoned investors have biases affecting their financial choices.

Roadmap to Retirement: Tax & Investment Strategies

Roadmap to Retirement: Tax & Investment Strategies

The journey into retirement requires a strategy. Check out these tax and investment strategies to help you grow your wealth.

Insuring Your Second Home

Insuring Your Second Home

There are unique risks of owning a second home and obtaining the proper coverage may protect you from financial risk.


Have A Question About This Topic?


Thank you! Oops!

Retirement Is a Beginning

Key questions to answer when you are considering retirement.

How to Effectively Budget as a Couple

Be sure that you agree on how to go about combining your finances as a couple before discussing how you'll handle expenses.

What Is a Roth 401(k)?

Roth 401(k) plans combine features of traditional 401(k) plans with those of a Roth IRA.

View all articles

Student Loan Refinance Calculator

Compare your current student loan terms to a potential refinance to see if it makes sense.

Comparing Mortgage Terms

Compare different mortgage term lengths side by side to find the option that fits your budget.

How Long Will Your Money Last?

See how long a lump sum of savings could last based on your withdrawal rate and return.

View all calculators

Charitable Giving: Smart from the Heart

Do you have causes that you want to support with donations?

Once Upon a Goal

Do you know how to set up your financial goals for success? This knight does.

When Do You Need a Will?

When do you need a will? The answer is easy: Right Now.

View all videos